

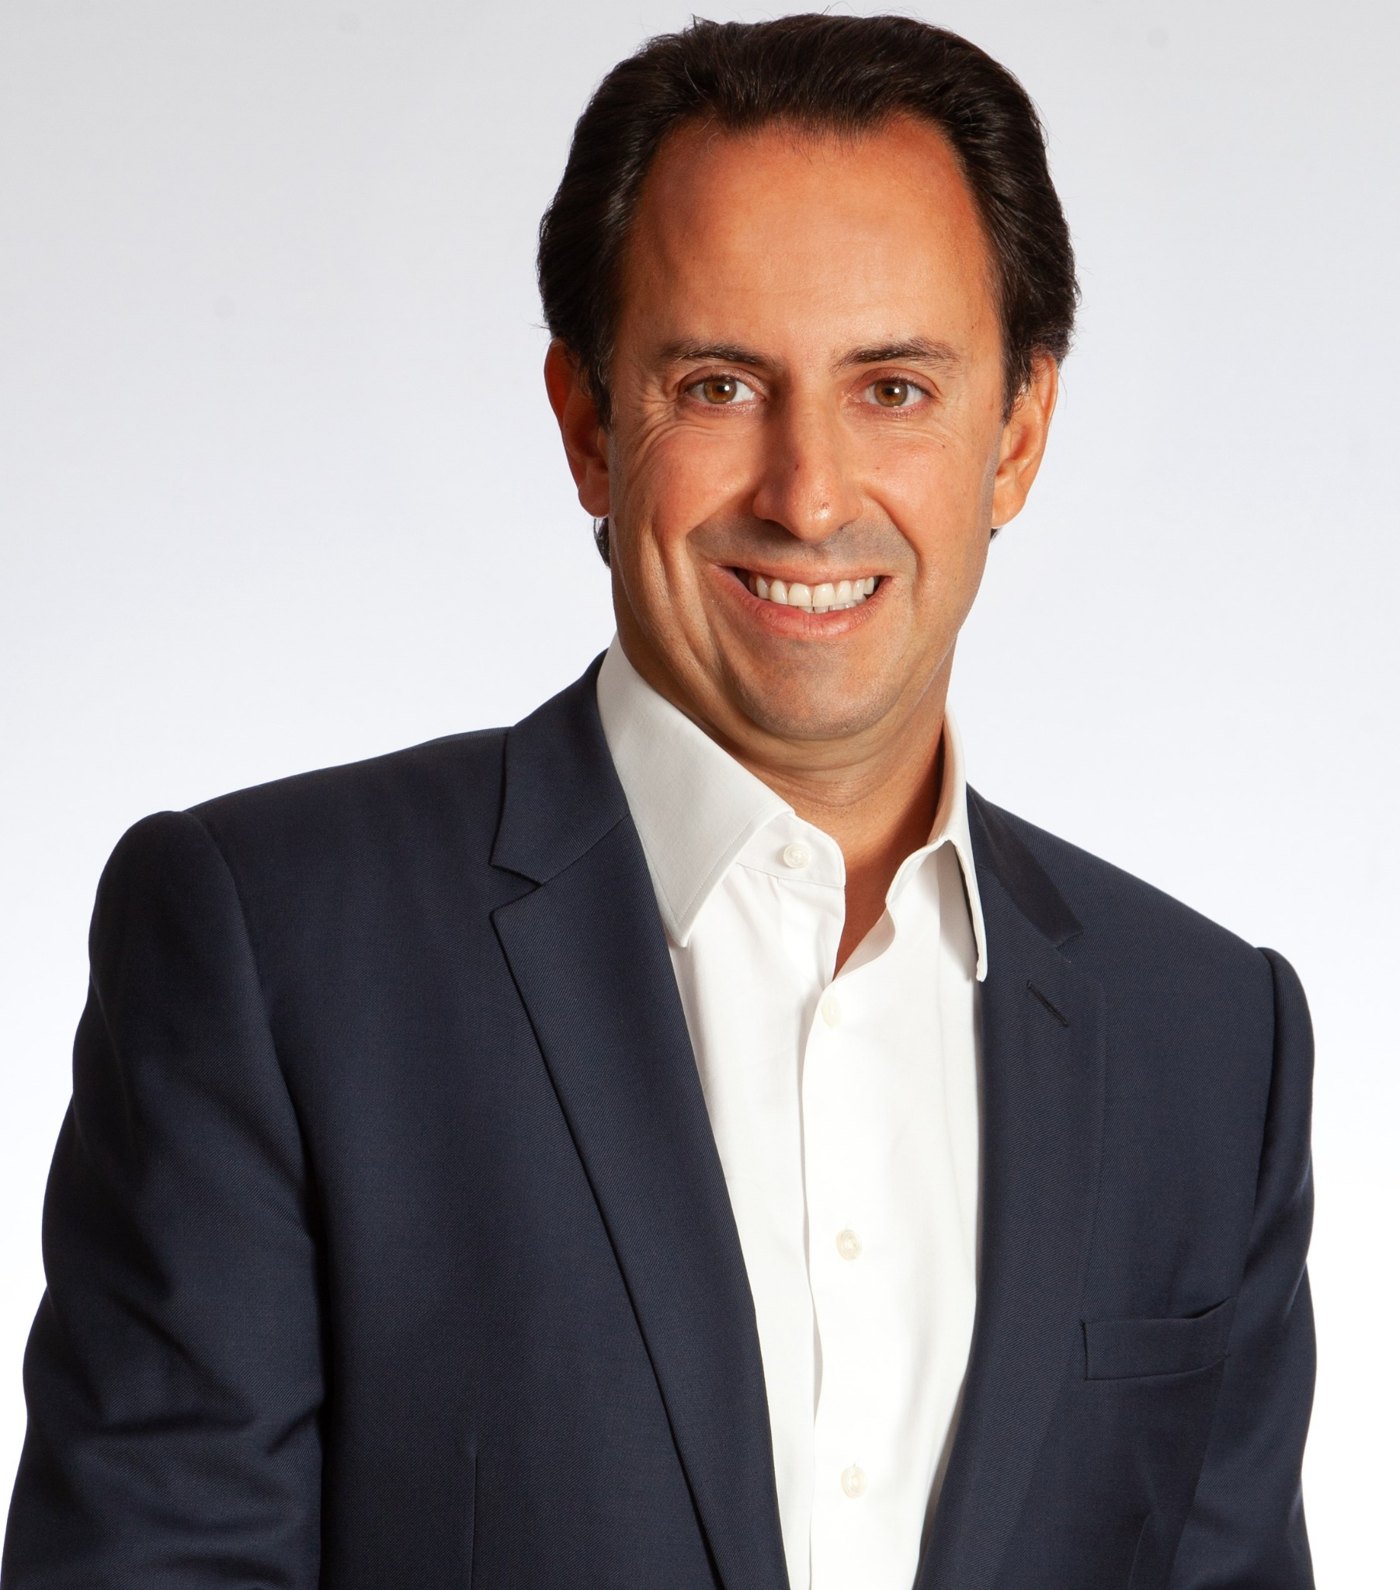

Chairman Julien Balkany explains how contracted domestic gas complements Panoro’s oil production—and how acquisitions compete with investment in existing assets. His comments were supplied before the 24 October Dussafu rig incident.
Panoro Energy is adding contracted gas revenue to an African portfolio built largely around oil, while committing further capital to the assets it already owns.
Its acquisition of an indirect 9.09% interest in Block CI-27 offshore Côte d’Ivoire, completed in September, brings a fourth producing country into the portfolio. Operated by Foxtrot International, the asset supplies gas for electricity generation in Abidjan, connecting Panoro’s upstream investment to domestic power demand.
For Julien Balkany, Chairman of Panoro Energy ASA, the acquisition diversifies the company’s exposure while remaining within its stated investment criteria.
“It is a broadening, not a change of direction,” he told AfricaBusiness.com. “Our criteria are clear: producing or near-producing assets in Africa that are accretive and that we understand technically.”
The distinction matters because Panoro’s growth plans continue to depend on both acquisitions and development work across its existing African operations. Côte d’Ivoire adds contracted gas alongside oil production in Equatorial Guinea, Gabon and Tunisia.
Following completion of the acquisition in September, Panoro put pro forma group production above 21,500 barrels of oil equivalent per day, or boepd. In comments supplied before the 24 October Dussafu incident, Balkany identified 23,000 boepd as the targeted average production for 2027. These figures should not be read as a post-incident production update or reaffirmed guidance.
What Côte d’Ivoire gas adds to the portfolio
CI-27 offers a different revenue structure from the company’s oil assets. Approximately 95% of the acquired production is gas, sold under long-term take-or-pay arrangements with a minimum fixed price in US dollars that is de-linked from oil prices.
That provides a contractual basis for revenue planning alongside exposure to international oil markets. It does not establish that financial results are risk-free. Panoro’s published disclosures identify uncertainties associated with production, development expenditure, counterparties and regulation, among other factors.
The current production-sharing contract runs to August 2034.
Maintaining production requires continuing investment. According to Panoro, the operator’s five-well infill programme at Foxtrot is intended to sustain a gross gas production plateau of approximately 190–200 million standard cubic feet per day, with scope to increase deliveries to around 230 million if demand supports it.
Those figures refer to the asset’s gross gas output. Production attributable to Panoro’s acquired interest was approximately 3,300 boepd in the periods reported when the transaction was announced.
For the company, the commercial opportunity therefore combines an established customer market, existing infrastructure and further investment to sustain deliveries.
Acquisition funding and capital allocation
The acquisition also illustrates the funding decisions behind Panoro’s expansion. The transaction was announced at $80 million on a cash-free, debt-free basis, with an effective date of 1 January 2025 and subject to customary adjustments.
At completion, consideration totalled $64.4 million: $43 million in cash and $21.4 million through the issue of seven million Panoro shares to DNO. A $5 million cash deposit had been paid previously. These amounts distinguish the announced transaction value from the cash and shares transferred at closing.
The financing announced alongside the acquisition included a $50 million senior unsecured bond carrying a 10.25% coupon and maturing in 2031. Financing costs are therefore part of the investment case, alongside the asset’s reported production cost of approximately $6 per barrel of oil equivalent. That operating-cost figure is not an all-in measure of acquisition, financing and development expenditure.
Balkany said acquisitions and spending on existing assets are assessed against the same capital-allocation discipline.
“They compete for the same capital on the same terms, and this year both have earned it.”
Balkany put pro forma 2026 capital expenditure at approximately $72 million, including around $20 million attributable to Panoro’s interest in CI-27. The wider programme includes investment in Gabon and work on Block G in Equatorial Guinea.
Dussafu incident changes the operating context
Gabon illustrates the execution risks alongside the growth opportunity. On 15 October, Panoro outlined a planned four-well MaBoMo Phase 2 campaign at Hibiscus and Hibiscus South, with the first new well then expected onstream in early 2027.
The joint venture was also assessing a fifth production well following successful appraisal drilling. Those plans preceded the subsequent rig incident.
On 25 October, Panoro reported that Borr Drilling’s Prospector 5 had lost stability and sunk during jacking operations on 24 October. It said MaBoMo production was shut down during drilling preparations and reported no damage to the facility. Panoro holds a 17.5% non-operated interest in Dussafu.
In its 29 October update, Borr Drilling said 110 of the 115 personnel aboard had returned ashore. It reported that the bodies of three people had been located, while two remained unaccounted for and search and recovery efforts continued. These figures describe that dated update.
The statements cited here do not establish a revised drilling timetable or quantify the effect on Panoro’s 2027 production ambition. The earlier early-2027 well start-up expectation therefore remains a pre-incident plan.
Further ahead, Balkany identified the sanctioned Bourdon development, which had targeted first oil in the first half of 2028, as another component of the growth programme. In Equatorial Guinea, well interventions and work at Ceiba form part of efforts to improve recovery and production performance.
What to watch next
Panoro’s strategy consequently involves several distinct delivery tasks: sustaining contracted gas supply in Côte d’Ivoire, bringing new wells into production in Gabon, and improving performance from established oil assets.
The company did not identify specific future acquisition targets in the comments supplied for this feature. Balkany emphasised producing or near-producing African assets that meet its technical and financial criteria.
For the next phase, the clearest measures of progress will be the production and drilling outlook following the Dussafu incident, execution across the portfolio, and the conversion of contracted sales into cash after operating, investment and financing costs.
Reporting is based on written responses supplied by Panoro Energy, subsequent clarifications from its representative, and the company’s published disclosures.
Related reading: Panoro Energy Completes Acquisition of Stake in Côte d’Ivoire’s CI-27 Gas Block.
Sources and photograph
Panoro: acquisition completion, 14 September 2026
Panoro: Dussafu appraisal update, 15 October 2026
Panoro: Dussafu incident, 25 October 2026
Borr Drilling: incident update, 29 October 2026
Julien Balkany, Chairman of Panoro Energy ASA. Photograph: Panoro. Comments were supplied before the 24 October incident; this feature incorporates company statements issued subsequently.